
How to pay Chinese suppliers is one of the most critical questions international buyers face. The answer is not just choosing between bank transfer, card or an online platform. The safer decision connects four things: the verified legal supplier, the correct beneficiary account, a written order, and payment milestones tied to evidence.
No payment method can rescue a poorly defined order. Before sending funds, confirm exactly what will be produced, when each payment becomes due, what evidence releases it and what happens if the goods do not match the agreement.

This guide explains the main ways importers pay Chinese suppliers and the controls to complete before authorising a transfer.
Complete these checks before choosing a payment method
Start with the transaction, not the supplier’s preferred payment channel.
- Verify the supplier’s registered company name and the party named on the quotation, contract and invoice.
- Confirm the product specification, quantity, approved sample or reference, packing, delivery term and required date in writing.
- Identify the beneficiary name, bank country and reason if the account holder differs from the contracting party.
- Define what is due before production, after an approved milestone and before shipment.
- Decide what inspection, document or approval will support each release.
- Record who inside your company can approve a new beneficiary or a change of bank details.
If the commercial party, invoice issuer and beneficiary do not align, stop and obtain a documented explanation. A sourcing structure may involve an authorised trading or service company, but that relationship should be understood before payment rather than discovered after a dispute.
How to Pay Chinese Suppliers: 5 Proven Methods

1. Bank transfer
A bank transfer is widely used for business-to-business orders. It creates a clear transaction record and can suit a supplier with a verified company account. Its main weakness is that a transfer is difficult to reverse after the receiving bank credits the funds.
Before sending a bank transfer, match the beneficiary against the signed order and confirm any changed instructions through a known contact using a second channel. Do not rely on replying to the message that announced the change.
2. Platform payment with order protection
A marketplace or sourcing platform may offer payment processing and order protection. The protection is not automatic merely because the supplier has a profile on the platform. The order, specification, shipment terms and payment normally need to remain inside the platform and comply with its current rules.
Read the protection terms for the actual order. Check what evidence is required, which events are covered, the dispute deadline and whether any part of the payment will occur outside the protected transaction.
3. Card or digital wallet
Cards and digital wallets can be practical for samples, small orders or approved platform transactions. Availability, limits, fees and dispute rights depend on the provider, account and transaction. Confirm these conditions before treating the method as protection.
Do not split a large purchase into informal personal payments simply to bypass a platform or bank control. The payment record should still identify the commercial order and recipient.
4. Letter of credit or another bank-assisted trade instrument
A letter of credit may be considered for a larger transaction when the buyer and supplier can agree clear documentary conditions. It involves banks and documents, but it does not independently prove product quality. Poorly drafted conditions can create cost and delay without solving the underlying specification risk.
Use trade-finance and legal advisers to confirm the current instrument, documents, fees and responsibilities. Keep product inspection and acceptance controls separate from documentary compliance.
A buyer working with a sourcing company may make one payment to the authorised service provider, which then pays and coordinates approved suppliers. This can simplify several-factory orders, local-currency payments, invoices and consolidation.
Verify the sourcing company’s legal identity, service agreement, fee, custody or release process, supplier-payment records and responsibility if an order changes. One combined payment is useful only when the underlying supplier orders remain transparent.
Which payment method fits which situation?
| Situation | Method to evaluate | Main control |
|---|---|---|
| Sample or small test order | Approved platform, card or wallet | Keep the order and payment record linked; confirm provider terms |
| Verified supplier and repeat B2B order | Company bank transfer | Reconfirm beneficiary and milestone evidence |
| Platform-sourced order | Platform protection | Keep specifications, communication and payment inside the protected order |
| Larger documentary transaction | Bank-assisted trade instrument | Use professionally drafted conditions and separate quality inspection |
| Order involving several Chinese suppliers | Authorised sourcing-company payment | Maintain supplier-level quotations, approvals and payment records |
The best method is the one whose cost, evidence and remedy fit the actual order. It is not necessarily the method with the lowest visible transfer fee.
Link every payment to an order milestone
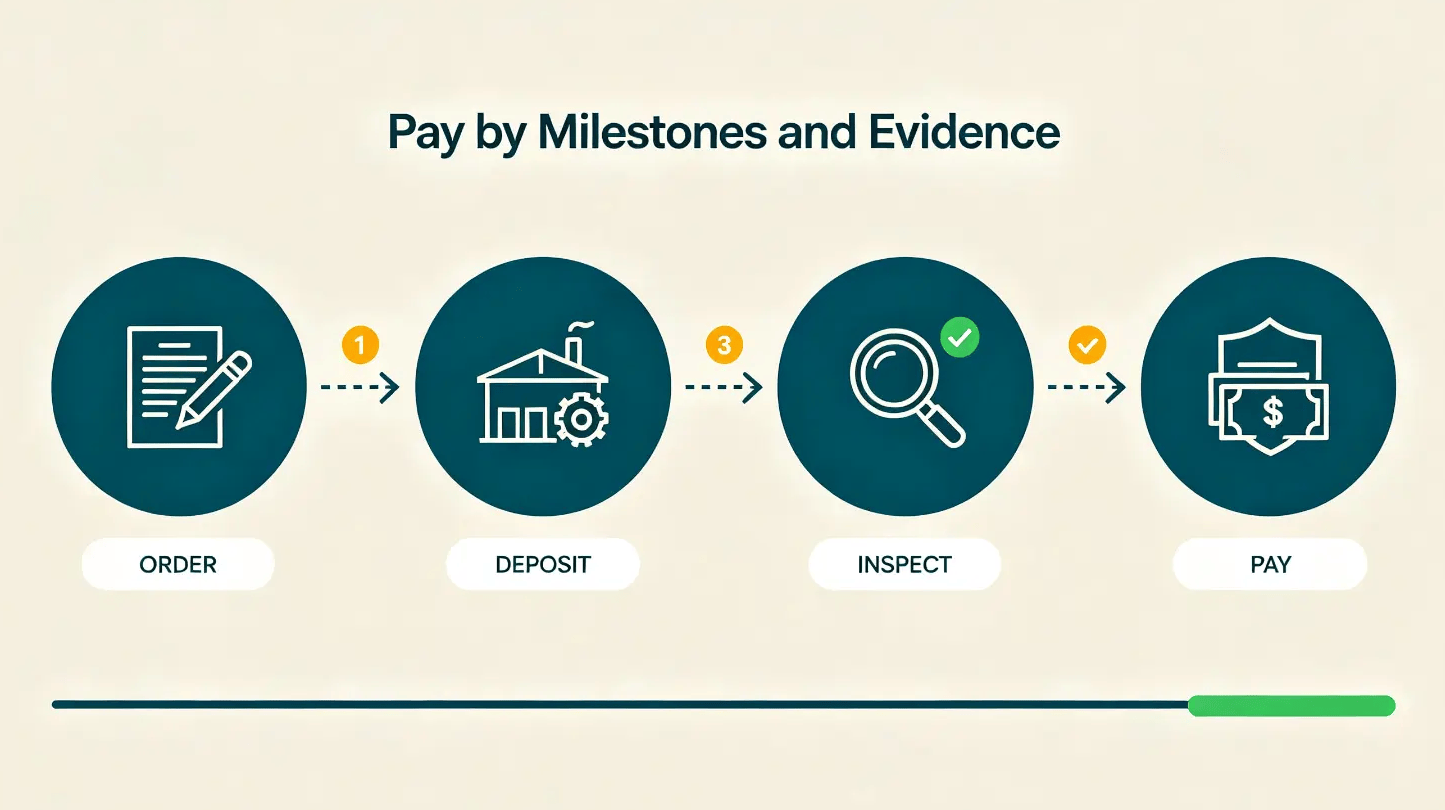
Do not release money because a calendar date arrived or a supplier sent a general progress message. Write the milestone and its evidence before production starts.
Depending on the order, useful evidence can include:
- a signed specification and commercial order;
- an approved sample, drawing or packaging file;
- material or component confirmation where it matters;
- production records against the approved version;
- a completed inspection report with resolved non-conformities;
- packing, quantity and shipping documents that match the order.
The percentage and timing are commercial decisions, not universal rules. Confirm them for the supplier, product, order value, production process and available leverage. Do not copy a standard deposit formula into every purchase.
Prevent bank-detail and invoice fraud
A legitimate supplier’s email account can be compromised. A convincing message may preserve the normal signature, invoice format and conversation history while replacing the beneficiary details.
Use a written change-control process:
- Treat every new beneficiary or bank-detail change as unverified.
- Call a known contact using a number already held in your records, not one supplied in the change message.
- Ask a second authorised person to compare the invoice, contract and beneficiary.
- Record the confirmation before the transfer is approved.
- If a transfer appears fraudulent, contact your bank immediately about recall or recovery procedures and report the incident through the appropriate authority.
Urgency, secrecy, a last-minute account change or pressure to bypass the normal approver is a reason to stop, not a reason to move faster.
What payment evidence should an importer keep?
- the final quotation, purchase order and contract version;
- supplier identity and beneficiary verification;
- approved specification, sample and packing files;
- platform order or bank reference;
- milestone approvals and inspection records;
- commercial invoice, packing list and shipping documents;
- records of any authorised change.
These records support internal control and faster investigation. They do not guarantee a refund, but they are far stronger than an informal chat and an unverified invoice.
How Minden Intl supports supplier payments
Minden Intl helps international buyers verify suppliers, compare quotations, define order requirements, coordinate samples and production, inspect goods, consolidate shipments and maintain supplier-level records. Read the separate Chinese supplier verification checklist before approving a new factory.
For platform orders, keep the platform’s current protection requirements in view. For direct orders, make the supplier, beneficiary, specification and milestone evidence traceable before payment.
Send us the supplier quotation, product requirements and proposed payment instructions. We will identify the missing checks before you authorise the transfer.
Frequently asked questions
What is the safest way to pay a Chinese supplier?
No method is safest in every situation. The practical choice depends on the verified recipient, order value, written terms, milestone evidence and the protection actually available from the bank or platform. or platform.
Should I pay a Chinese supplier’s personal account?
A personal or unrelated account creates an identity and recovery risk. Stop and ask why the beneficiary differs from the contracting party. Proceed only after the commercial relationship and responsibility are verified and documented.
Does Trade Assurance protect every Alibaba payment?
No. Protection depends on the eligible order, its agreed terms, payment through the platform and the current Trade Assurance rules. Read the terms for the specific transaction and keep the order evidence inside the platform.
When should the final supplier payment be released?
The order should define this in advance. Release should be tied to the agreed milestone and supporting evidence, such as resolved inspection findings and correct shipping documents, rather than a generic timetable.